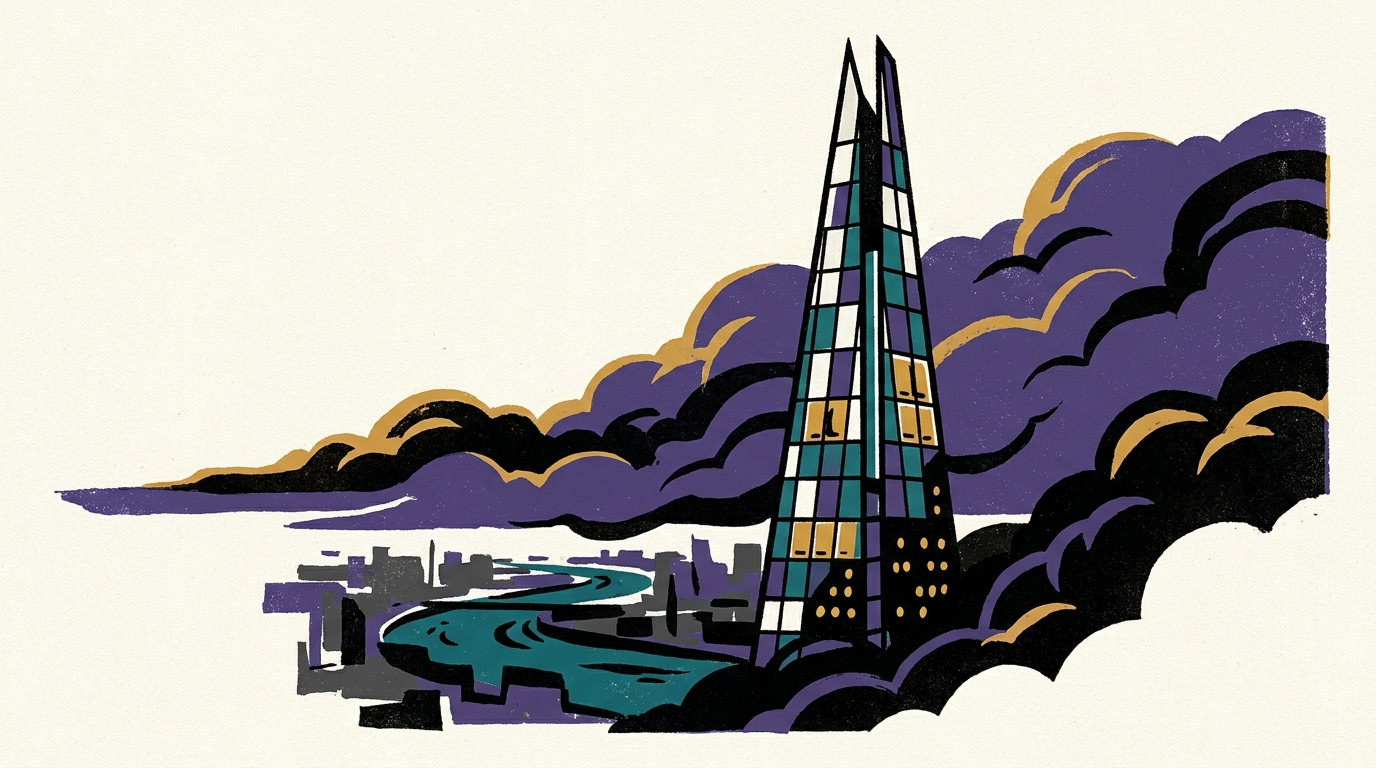
The Shard’s Fifty-Million-Pound Empty Apartments and the Rise of the Shadow Hotel
How ten unsold ultra-premium penthouses at the top of London’s tallest tower became a private, high-ticket short-term rental operation for global elites.
High above the Southwark pavement, where the London damp meets the steel-and-glass point of the Shard, ten residences have spent twelve years waiting for owners who will never arrive. These are not ordinary apartments; they are vertical estates, originally priced at fifty million pounds each, designed to be the ultimate trophies in a city that spent the last two decades positioning itself as the playground of the global wealthy. Yet, since the tower was completed in 2012, not a single one of these homes has been sold to a private buyer. Instead of a bustling vertical neighborhood of billionaires, the upper reaches of Europe’s most recognizable skyscraper have remained largely dark, a monument to a property market that overshot its own limits.
But the lights are not entirely out. As revealed by London Centric, these unsold assets have quietly found a secondary purpose, one that bypasses the conventional sales market entirely. The developer has turned these fifty-million-pound spaces into what is effectively an exclusive, unlisted short-term rental network for the world’s most affluent travelers. It is a shadow operation that some have dubbed an Airbnb for sheiks, where royal families, sovereign wealth operators, and ultra-high-net-worth individuals rent out entire floors of the tower for days, weeks, or months at a time. It is short-term rental execution on a scale that makes the typical vacation rental manager look like they are playing with pocket change.
For the global short-term rental industry, this is more than just a piece of high-society gossip. It is a case study in how institutional real estate uses the mechanics of short-term letting to solve a balance-sheet crisis. When a property cannot sell at its target price, and when dropping that price would trigger a catastrophic revaluation of an entire portfolio, the short-term market offers a convenient back door. By operating these units as ultra-premium temporary residences, the owners can generate yield, justify the nominal value of the assets, and keep the property off the traditional market until the macroeconomic winds shift. It is a playbook that is being quietly replicated in major cities around the globe, and it reveals a double standard at the heart of municipal housing policy.
What happened
According to an investigation by London Centric, the ten residences occupying floors fifty-three to sixty-five of the Shard have remained unsold since the building opened twelve years ago. The properties, which were marketed with a target price of up to fifty million pounds each, represent a combined value of half a billion pounds. The Shard is ninety-five percent owned by the State of Qatar, with the remainder held by the estate of developer Irvine Sellar. Despite the prime location and the architectural significance of the building, the developers have steadfastly refused to lower their asking prices to meet the reality of the London luxury market.
Rather than allowing the units to sit entirely dormant and generate nothing but holding costs, the operators have transitioned them into a highly discreet, ultra-exclusive short-term letting operation. London Centric reports that these apartments are being let out to wealthy Middle Eastern visitors, foreign dignitaries, and members of Gulf royal families who require immense security, privacy, and space during their stays in the British capital. These are not listings that can be found on public platforms like Airbnb, Vrbo, or Booking.com. Instead, they are booked through highly specialized, private channels, family offices, and elite concierge services that cater exclusively to the top fraction of a percent of global wealth.
This transition has allowed the Shard’s owners to generate substantial revenue from assets that would otherwise be dead weight on their books. It also allows them to maintain the fiction of the fifty-million-pound valuation. If they were to sell one of these apartments for thirty million pounds—which is closer to what market experts estimate their actual value to be in the current economic climate—they would be forced to revalue the remaining nine units downward. That would represent a paper loss of two hundred million pounds across the portfolio, an outcome that the Qatari sovereign wealth fund is desperate to avoid. By keeping the units in the short-term rental pool, they can argue that the assets remain premium, high-yielding properties waiting for the right buyer.
The financial engineering of the valuation trap
To understand why the Shard’s owners prefer to run an elite lodging house rather than cut their prices, one must look at the mechanics of institutional real estate finance. In the world of sovereign wealth and mega-developments, a property’s book value is often far more important than its immediate liquidity. The State of Qatar, which backs the Shard, holds a ninety-five percent stake in the tower. For an entity of this size, the Shard is not just a building; it is a flagship asset that anchors their London portfolio.
When an institutional owner takes out debt against a real estate portfolio, the terms of those loans are tied directly to the appraised value of the assets. If the appraised value drops, it can trigger loan-to-value covenants, forcing the owner to either inject massive amounts of cash or face penalties from their lenders. Selling a single apartment at a discount of twenty million pounds would establish a hard market comparable. Appraisers would use that sale to recalculate the value of the remaining units. Suddenly, a half-billion-pound residential portfolio is worth only three hundred million pounds, creating a massive hole on the balance sheet.
By operating the apartments as short-term rentals, the owners can exploit an accounting loophole. The properties remain classified as residential assets held for sale, but they generate operational income that can be used to offset the immense maintenance and service charges associated with keeping a supertall skyscraper functioning. The short-term rental market, in this context, serves as a financial shock absorber. It allows the owners to kick the valuation can down the road indefinitely, avoiding a painful write-down while waiting for a market recovery that may take decades to materialize.
Inside the shadow booking network of the ultra-wealthy
The hospitality operations at the top of the Shard bear no resemblance to the standard short-term rental model. There are no key lockboxes, no self-check-in instructions sent via automated messages, and no host profiles promising a local experience. The world of ultra-high-net-worth short-term rentals is entirely hidden from public view, operating on a basis of absolute discretion and personal relationships.
Bookings are managed through a network of elite destination management companies, family offices, and ultra-high-end concierge services. When a member of a Gulf royal family or a foreign industrialist plans a summer visit to London, their personal staff does not browse booking websites. They contact specialized brokers who control access to off-market properties. These brokers act as gatekeepers, vetting guests for security, financial standing, and reputation before any contract is signed.
The operational logistics of these lets are similarly complex. The Shard’s residences sit directly above the Shangri-La Hotel, which occupies floors thirty-four to fifty-two. This vertical proximity is not accidental. It allows the operators of the residences to draw upon the hotel’s infrastructure, including room service, housekeeping, security, and concierge services, without having to maintain a dedicated hospitality staff for ten empty units. The result is a hybrid model that combines the privacy and space of a mega-apartment with the operational support of a five-star hotel. Guests pay astronomical daily rates—often reaching tens of thousands of pounds per night—for a level of service and security that no standard hotel suite can match.
The London regulatory double standard and the ninety-day loophole
While the Shard’s owners enjoy the benefits of a highly lucrative, off-market short-term rental operation, London’s ordinary hosts find themselves under increasingly strict regulatory surveillance. Under the Greater London Council Act 1973, as amended by the Deregulation Act 2015, residential properties in London are subject to a strict ninety-day annual limit on short-term letting. Any host who lets out an entire property for more than ninety nights in a calendar year must obtain planning permission for a change of use from the local council.
Southwark Council, the local authority with jurisdiction over the Shard, has been one of the most vocal critics of the short-term rental boom in London. Like many central London boroughs, Southwark has struggled with a severe housing shortage and rising rent prices. The council has repeatedly cracked down on unauthorized short-term lets, using data-scraping software and neighbor complaints to identify hosts who exceed the ninety-day limit. Ordinary property owners who violate the rules face enforcement action, steep fines, and the threat of court orders.
Yet, the Shard’s residences appear to operate in a regulatory vacuum. Because these bookings are handled privately and often structured as short-term corporate tenancies or high-value license agreements rather than standard holiday lets, they frequently escape the scrutiny of local planning enforcement. Furthermore, the immense political and economic influence of the Qatari state, which has invested billions of pounds across London—including ownership of Harrods, Chelsea Barracks, and the Olympic Village—creates a formidable barrier to aggressive regulatory intervention. This stark double standard has not gone unnoticed by the local hosting community, who argue that the rules are designed to penalize small-scale operators while turning a blind eye to institutional workarounds.
Comparable playbooks from Manhattan to Dubai
The phenomenon of using short-term rentals to park distressed luxury assets is not unique to London. In New York City, the rise of Billionaires’ Row along Fifty-Seventh Street has created a similar dynamic. Ultra-luxury towers like One57 and 432 Park Avenue have seen numerous units sit empty for years after being purchased by foreign investors. When the market cooled, some of these owners turned to high-end corporate leasing and short-term rentals to cover their high monthly carrying costs and property taxes. However, New York’s aggressive crackdown on short-term rentals through Local Law 18 has made this strategy far more difficult, forcing some owners to pivot to medium-term corporate stays of thirty days or more.
In Dubai, the luxury short-term rental market has become an integral part of the city’s real estate ecosystem. Developers routinely build high-end residential towers with the explicit intention of operating them as serviced apartments or short-term holiday homes. The regulatory environment there is highly supportive of this model, with clear licensing frameworks that allow institutional owners to easily transition properties between long-term leases, short-term rentals, and outright sales depending on market conditions.
In Paris, the market for private mansions and historic apartments is heavily regulated, but a thriving shadow market of high-end rentals still exists to serve wealthy international visitors. The city’s strict four-month limit on short-term lets of primary residences has forced professional operators to focus on high-value corporate rentals and medium-term tenancies that fall outside the standard tourism regulations. What these global gateway cities show is that where there is highly valuable, underutilized real estate, capital will always find a way to monetize it through flexible, short-term accommodation models, regardless of local regulatory frameworks.
Sovereign wealth and the long horizon
To fully grasp the dynamics at play in the Shard, one must understand the unique nature of sovereign wealth fund investing. Unlike private equity funds or traditional real estate developers, which typically operate on five-to-ten-year fund lifecycles, sovereign wealth funds like the Qatar Investment Authority operate on a multi-generational horizon. They do not need to liquidate assets to return capital to investors. They can afford to wait decades for a market to turn in their favor.
This long horizon changes the entire calculation of holding costs. The financial pain of keeping ten ultra-premium apartments empty is negligible for a sovereign state with vast resources. The priority is not quick cash flow, but capital preservation and political influence. The Shard is a physical manifestation of Qatar’s economic presence in London, a monument of soft power that sits on the skyline. Selling the residences at a discount would not only hurt the fund’s balance sheet; it would also be a public admission of commercial failure.
Therefore, the transition to a short-term rental model is not a sign of desperation, but a highly calculated holding action. It provides enough revenue to make the assets self-sustaining while preserving the option of a future high-value sale. It is a luxury that only the most heavily capitalized owners can afford, and it highlights the growing divide between institutional players who can write their own rules and individual hosts who must operate within the strict confines of municipal law.
Who wins and who pays the holding cost
In this high-stakes game of real estate hiding-and-seeking, the distribution of benefits and losses is highly unequal. The clear winner is the developer, Real Estate Opportunities Limited, and its Qatari backers. By keeping these apartments off the sales market, they have successfully defended the theoretical value of their portfolio. They have avoided the public embarrassment of a fire sale, maintained their borrowing power, and generated enough cash flow from elite rentals to cover their operational overhead.
The losers are the citizens of London and the local housing market. These ten residences represent prime residential space in the heart of a city facing a chronic housing crisis. While fifty-million-pound apartments were never going to house schoolteachers or nurses, their complete withdrawal from the active housing stock represents a broader trend of financializing real estate at the expense of community utility. Furthermore, the local council misses out on the substantial Council Tax revenue that would be generated by occupied, primary residences, while the local economy receives only a fraction of the benefit that would come from a stable, year-round residential population.
The traditional hotel sector also loses out on high-value bookings. Ultra-premium travelers who might have otherwise booked the presidential suites at five-star hotels like the Savoy, the Dorchester, or indeed the Shangri-La itself are instead staying in private, unlisted residences that operate with lower regulatory and tax burdens. This creates an uneven playing field, where institutional real estate owners can compete directly with established hotel brands without having to comply with the same stringent commercial property regulations and tax structures.
While municipal authorities hunt down mom-and-pop hosts for exceeding the ninety-day limit, sovereign wealth funds run a half-billion-pound unlicensed hotel at one thousand feet in the air.
“The transition to high-value, unlisted short-term lets has allowed the Shard’s owners to maintain the fiction of the fifty-million-pound valuation while avoiding the pain of a write-down.”
What hosts should do now
The Shard’s shadow rental operation reveals that the high-ticket segment of the short-term rental market operates on entirely different principles than the mass market. Professional hosts and portfolio managers should adapt their strategies to capitalize on these institutional playbooks.
- Diversify away from public OTA platforms: Transition your highest-value properties off public listings like Airbnb and onto private, off-market channels. Build relationships with family offices, corporate relocation agents, and high-end concierge services that manage travel for affluent clients.
- Exploit the medium-term corporate loophole: In markets with strict short-term rental limits like London’s ninety-day rule, focus on corporate tenancies and stays of over ninety days. These bookings are often exempt from municipal caps and offer stable, high-yield occupancy.
- Form strategic partnerships with luxury hospitality brands: If you operate premium properties, seek partnerships with nearby five-star hotels to offer overflow accommodation or adjacent services, mimicking the Shard’s relationship with the Shangri-La.
- Focus on security and privacy infrastructure: Upgrade your high-end properties with commercial-grade security systems, private access points, and strict non-disclosure protocols to attract corporate executives and high-net-worth individuals.
- Monitor sovereign wealth and institutional real estate movements: Watch where major institutional capital is buying or holding vacant luxury stock. These areas are prime markets for high-value corporate and temporary housing services.
Ultimately, the Shard’s empty apartments prove that the short-term rental model is no longer just a way for homeowners to make extra cash; it is a sophisticated financial tool used by the world's most powerful institutions to manage risk and defend capital. By understanding and adopting these strategies, professional operators can position themselves to thrive in an increasingly regulated and institutionalized market.
Checked by the standards desk (Eleanor Quist): 3 specifics were removed or attributed as unverified before publication.
Read the desk every morning.
The day's crackdowns and platform moves, the money, the design and the stays going viral, plus the desk's verdict, in one short email every morning.